 Silofinance
 risk isolation - V3 collateral exposure and lender recovery
Silofinance risk isolation confines collateral exposure to a selected Silo V3 market, while managed vault deposits can span several markets. Lenders remain exposed to the collateral that supports borrowing in each selected pair. Its value, price feed, and available liquidity influence the quality of that exposure. A managed vault's exposure reflects the markets to which its manager allocates deposits. V3 also supports collateral-debt swaps (CDS), which can compensate lenders with collateral share tokens when that liquidation path operates. Compensation in collateral differs from repayment in the supplied asset. Market separation therefore needs to be read alongside the actual allocation, liquidation configuration, and ability to withdraw.
The boundary around the selected collateral
Collateral exposure remains inside the chosen market, so a weakening collateral position is a warning for lenders in that pair. A rising loan-to-value ratio indicates that debt occupies a larger share of the collateral valuation. This can reflect increasing debt, falling collateral value, or both. The relevant assessment concerns the affected market's coverage and liquidity. A separate market's collateral does not become security for this loan simply because both markets belong to Silo. Lenders can face a permanent loss if collateral becomes insufficient and liquidation fails to cover the debt.
Isolation bounds this credit exposure. Selling collateral requires trading liquidity, and withdrawing supplied tokens requires available market liquidity.
The V3 pair and its permitted direction
Silo V3 assigns distinct collateral and loan roles to its pair, with borrowing allowed in one direction within that market. Each V3 market consists of two single-asset vaults. The collateral asset supports borrowing of the loan asset, and the reverse direction is unavailable within that pair. Each market has its own collateral requirements and liquidation thresholds.
What does the supplied asset reveal about collateral exposure?
The supplied asset identifies what a lender provides, while the collateral asset identifies the backing for borrowing in that pair. In the V3 siUSD / USDC market, siUSD is collateral and USDC is the loan asset. The USDC denomination describes the lender's supplied token. It does not turn siUSD-backed credit into exposure solely to USDC.
The amount recorded in the supplied asset is also distinct from the value that collateral can realize during stress. Market-specific thresholds govern liquidation eligibility. They do not establish a permanent exchange price between the paired assets. Deposits denominated in the same token can therefore carry different collateral exposure when they belong to different markets.
Collateral valuation and borrowing limits
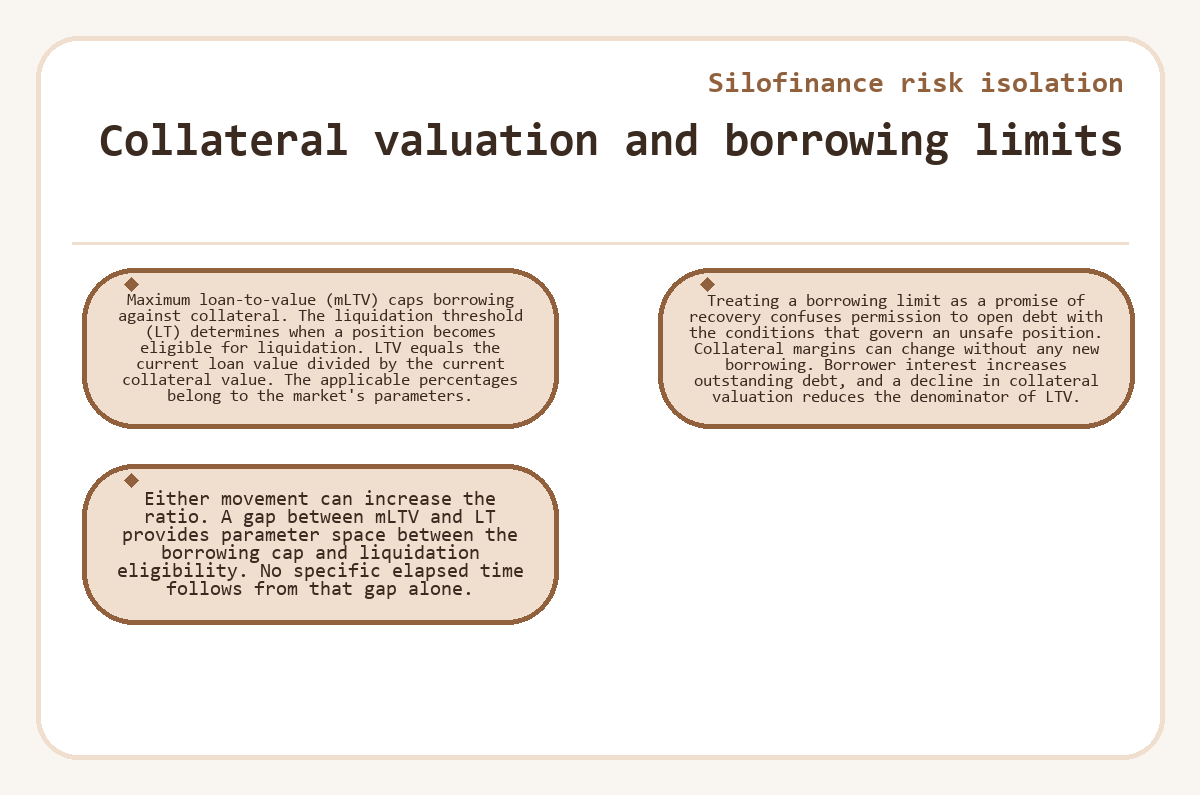
Maximum loan-to-value (mLTV) caps borrowing against collateral. The liquidation threshold (LT) determines when a position becomes eligible for liquidation. LTV equals the current loan value divided by the current collateral value. The applicable percentages belong to the market's parameters. Treating a borrowing limit as a promise of recovery confuses permission to open debt with the conditions that govern an unsafe position.
Collateral margins can change without any new borrowing. Borrower interest increases outstanding debt, and a decline in collateral valuation reduces the denominator of LTV. Either movement can increase the ratio. A gap between mLTV and LT provides parameter space between the borrowing cap and liquidation eligibility. No specific elapsed time follows from that gap alone.
Managed allocations and combined exposure
A managed vault can spread one deposit across several markets while leaving each underlying market's collateral exposure isolated from unrelated markets. Managers can allocate managed vault deposits among whitelisted silos. Depositors therefore hold exposure to the markets that actually receive those tokens. The vault's supplied asset and its underlying market allocation need to be considered together.
Current allocations show present exposure. The whitelist describes the markets that a manager may use, so present and permitted exposure can differ.
Delegating allocation changes who selects these exposures. It does not establish that every whitelisted market receives deposits or that allocation stays constant. The managed route also changes functionality: managed vault deposits cannot serve as borrowing collateral. Direct market deposits provide the borrowing route, subject to the pair's permitted direction and collateral limits.
Oracle prices within the market boundary
Oracle prices connect collateral valuation to borrowing and liquidation calculations, making the selected price methodology part of a market's exposure. The market's Risk section identifies its price sources, methodology, and referenced contracts. Those details explain what the protocol is valuing when it computes collateral coverage. A valuation method that tracks underlying value can differ from a price available in an immediate market sale.
Delayed or incorrect price data can distort the apparent relationship between debt and collateral. A position may look adequately covered even when a usable market price has changed. An incorrect price can also cause a healthy position to be liquidated. Each market remains dependent on its configured price feeds. Assessing collateral quality therefore includes how its price reaches the protocol, alongside what the token represents.
Can an isolated market run out of withdrawal liquidity?
An isolated market can become fully utilized, preventing withdrawals while supplied tokens remain on loan to borrowers in that market. Market separation does not create spare loan-asset liquidity. A utilization-responsive interest curve can encourage repayment and new deposits by increasing borrowing costs as liquidity tightens. Those incentives do not establish when enough underlying tokens will become available. The relevant withdrawal condition is available liquidity, which differs from collateral coverage and the interest rate displayed for the position.
Collateral sales and the lender's repayment asset
Collateral-sale liquidation aims to repay debt in the loan asset by exchanging seized collateral through a decentralized exchange (DEX). This path connects lender recovery to an executable collateral sale. Price impact and limited trading liquidity matter when the collateral is difficult to sell. A recorded valuation alone cannot complete that exchange. The incentive paid to a liquidator supports execution, while the market's configured threshold governs eligibility.
Eligibility and execution remain separate conditions. A qualifying position may still face insufficient trading liquidity or delayed liquidation. This can leave debt uncovered in the affected market. Isolation confines the collateral relationship, while the success of a sale depends on conditions at execution. This distinction also explains why V3 supports a separate mechanism that distributes collateral without requiring that market sale.
Does CDS return the asset that lenders supplied?
A Silo V3 collateral-debt swap compensates lenders with collateral share tokens when borrower debt is written off. No loan-asset transfer accompanies the simulated repayment. The Incentive Controller allocates collateral share tokens to lenders in proportion to their participation. Lenders must claim their allocations through the Silo lending app.
The protocol reduces the asset total recorded on the borrowed side by the forgiven debt amount. Clearing the borrower's debt therefore removes the corresponding claim on the original asset.
Collateral compensation leaves lenders exposed to that collateral's value and the conditions that affect realizing it. Avoiding a forced DEX sale removes that immediate execution requirement.
CDS can operate alongside standard collateral-sale liquidation, with a higher threshold when the sale path is also enabled. The applicable market configuration determines which mechanisms are available.
Contract failures outside collateral separation
Silo's smart contracts can contain accounting bugs or integration failures that cause deposit losses or blocked withdrawals. Audits and formal verification reduce risk without eliminating every failure mode.
Hooks, liquidation modules, and vault integrations add execution dependencies when included in a market. Their implementation matters alongside the collateral configuration that defines the market's intended exposure.
Choosing a direct market or managed allocation
A lender comparing a direct Silo V3 market with a managed vault needs to decide how broadly the deposit may carry collateral exposure. For an asset available through both routes, the supplied token can stay the same while responsibility for market selection changes. The direct route assigns that choice to the depositor. A managed vault delegates allocation among whitelisted markets.
- If exposure must stay with a selected pair, identify its collateral asset under Market.
- If allocation may span markets, review the managed vault's underlying exposures under Markets.
- Separate current allocations from the whitelist that defines the manager's permitted destinations.
- Keep the selected market's mLTV, LT, and enabled liquidation paths tied to that specific pair.
- Confirm that the displayed pair or allocation matches the exposure that the deposit is intended to carry.
Decide whether the chosen collateral exposure and available withdrawal liquidity suit the intended use of the deposit.
Things people ask about Silofinance risk isolation
Does spreading deposits across markets remove shared collateral exposure?
Market separation does not remove exposure to a collateral asset that several selected markets have in common. A price deterioration in that asset can matter to each affected position independently. Isolation keeps unrelated markets' lending relationships separate; it does not make shared collateral risks independent.
Can a Silo V3 market restrict who executes CDS?
CDS can use permissioned execution, limiting that path to approved actors. This configuration differs from the permissionless collateral-sale path. The existence of CDS support does not establish that every participant can trigger it in a particular market. Access restrictions belong alongside the enabled liquidation mechanisms when assessing how that market handles an unsafe position.
Which part of a CDS liquidation fee goes to lenders?
Silo V3 CDS assigns lenders 80% of the liquidation fee and assigns the liquidator the remaining 20%. Those percentages divide the fee, rather than the entire debt or deposit balance. Collateral-share allocations account for the forgiven debt and the lenders' fee portion, distributed pro rata. This reimbursement does not transfer the original loan tokens.
Why do collateral token transfer restrictions matter to isolated lenders?
A collateral token's pausing or blacklisting controls can affect transfers even when lending exposure sits inside an isolated market. Market separation does not remove controls in the underlying token contract. Such controls can constrain access to the underlying collateral that supports a share-token claim after CDS compensation.
When does the collateral-sale liquidation fee become fixed?
The deployer sets a market's collateral-sale liquidation fee, and the fee cannot change afterward. Its rate belongs to that market; it is not a universal percentage across Silo V3. The SiloConfig contract exposes the configured liquidation fee.
What happens to a small residual debt during collateral-sale liquidation?
A collateral-sale liquidation may clear the full position if a partial liquidation would leave an uneconomical dust balance. Silo V3 supports partial liquidations, but this condition can lead to full liquidation instead. Support for partial liquidation therefore does not promise that every qualifying position will retain a remaining balance.
Do borrowing and liquidation have to use the same oracle configuration?
An asset within a Silo V3 market can use separate oracle configurations for borrowing power and solvency calculations. The two uses therefore need not rely on an identical pricing configuration. A price supporting the borrowing limit does not, by itself, describe the valuation that governs liquidation eligibility.